Category: Uncategorized

  • US Buyers’ Paths to Lower Rates

    Navigating mortgage rates can feel overwhelming, especially when 30-year fixed rates sit in the mid- to high-6% range. As someone who believes in complete transparency and putting your interests first, I want to highlight some strategies that can help you secure a lower rate—and real savings—right now. Adjustable-rate mortgages (like a 7/6 ARM) are currently available in the low-6% range, a meaningful difference compared to fixed rates, but it’s vital to fully understand how resets and future adjustments could impact you down the line.

    Don’t underestimate the value of shopping around: even just one extra lender quote can save you an average of $1,500 over the life of your loan, and collecting five or more quotes can lead to an average savings of $3,000. If you’re seeing homes stay on the market a bit longer, now is a good time to negotiate for seller concessions that could fund temporary buydowns—helping ease those early payments without relying solely on future rate drops.

    The key is not simply waiting for the market to shift, but actively comparing lenders, exploring alternative loan structures, and negotiating strategically. With over two decades of experience and access to a wide range of programs, I’m here to help you find what actually fits your needs and budget.
  • FHA Loans During Peak Buying Season: How to Stay Competitive

    FHA Loans During Peak Buying Season: How to Stay Competitive

    Peak buying season always brings a flurry of activity—especially for those using FHA loans, which remain a favorite option for first-time buyers. Over my 23 years helping clients across the Bay Area, I’ve seen how preparation makes all the difference in this competitive landscape. Getting pre-approved early, understanding your true budget, and making sure your credit is in top shape set a solid foundation. Zeroing in on FHA-approved properties and working with a seasoned team can streamline the journey. Be ready to move quickly, present strong offers, and keep a bit of flexibility—these are the moves that can turn a crowded market into an opportunity. Above all, managing expectations is key. With the right strategy, navigating the FHA process can be less stressful and a whole lot more rewarding.

    Continue to full article

  • Conventional Loan Limit Rises to $845K

    Conventional Loan Limit Rises to $845K

    Starting Monday, September 21, 2026, the conventional loan limit increases from $832,750 to $845,000 for new locks. For San Francisco Bay Area buyers shopping in this range, the change may provide additional financing flexibility without stepping into jumbo territory. Government and jumbo limits remain unchanged. One important detail: appraisal waivers are not eligible for loan amounts between the old and new limits, so an appraisal may be required. If you are planning to buy or refinance, let’s review your scenario and see what you may now qualify for.

    Continue to full article

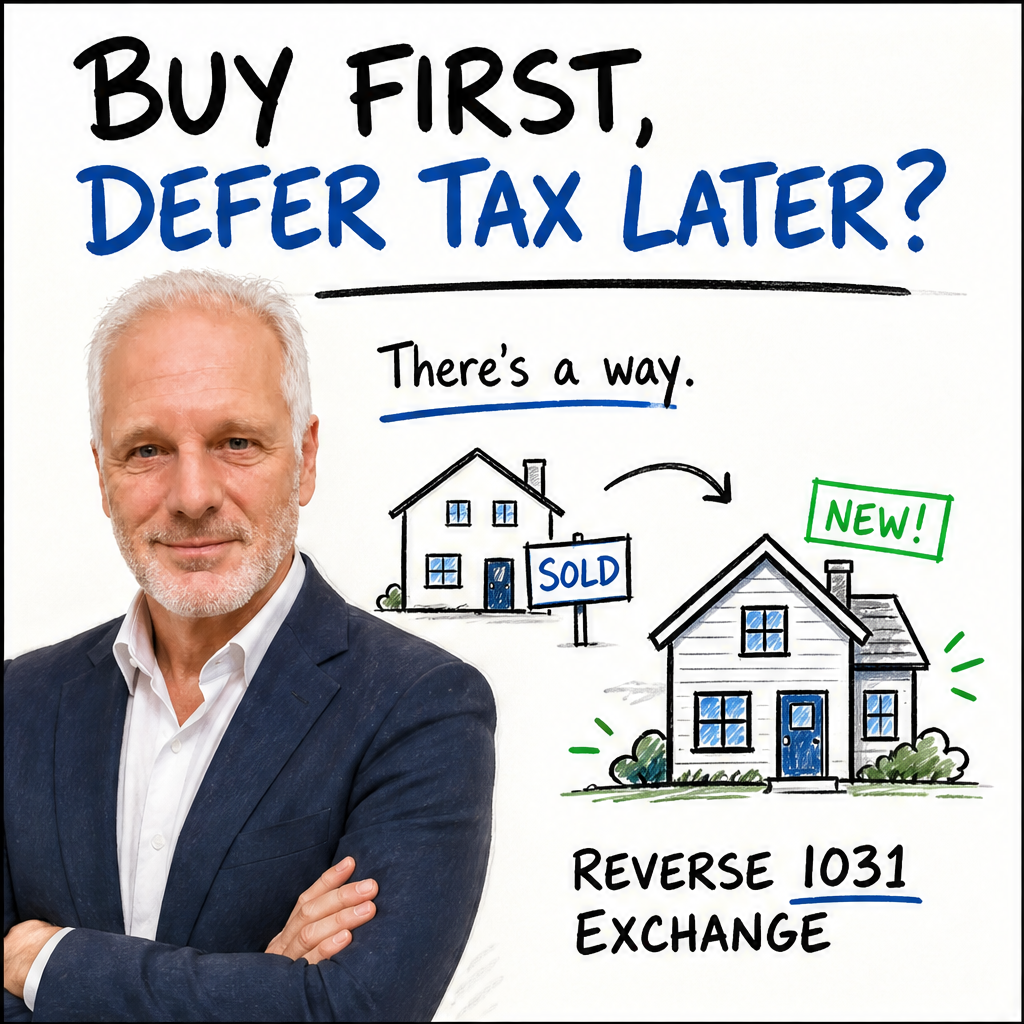
  • Reverse 1031 Exchange: Buy First, Defer Tax Later

    Reverse 1031 Exchange: Buy First, Defer Tax Later

    A reverse 1031 exchange can help real estate investors acquire a replacement property before selling the property they want to relinquish, potentially preserving tax-deferred exchange treatment when structured correctly. Success depends on early coordination among a mortgage broker, qualified intermediary, exchange accommodation titleholder, tax advisor, and other professionals. This guide highlights the essentials: assemble the right team, arrange financing and reserves, understand critical timelines, and document each step. Bay Area investors should seek personalized tax and legal advice before moving forward, while their mortgage broker helps evaluate practical financing options.

    Continue to full article

  • Balcony Solar Could Be California’s Next Big Breakthrough

    Balcony Solar Could Be California’s Next Big Breakthrough

    There's an intriguing development on the horizon in California: lawmakers are considering a proposal that would allow both renters and homeowners to set up portable solar panels right on their apartment balconies—and connect them directly to their household power. For those of us working through the intricacies of Bay Area homeownership and financing, this is more than just a tech upgrade. It’s a potential game-changer for clients who may not have access to traditional rooftop solar, especially in multi-unit buildings. Over my 23 years helping buyers, I’ve seen how the right innovation—paired with smart financing—can empower families to take control of their energy choices and monthly expenses. It’s these kinds of solutions that can turn a complex real estate landscape into one filled with new opportunities.

    Continue to full article

  • Why a mortgage rate lock makes sense this September

    Why a mortgage rate lock makes sense this September

    In recent months, we’ve seen the 30-year mortgage interest rate edge up to 6.87%—more than a full percentage point above where it stood just half a year ago. Having navigated hundreds of rate cycles across the Bay Area, I know how quickly these changes can impact a buyer’s bottom line. With the Federal Reserve signaling possible further hikes, and lenders often following suit, locking in your rate this September can be more than just a smart move—it’s a way to bring clarity and control to an often unpredictable process. My approach has always been to help borrowers understand their options and shield themselves from surprise costs. In moments like these, a well-timed rate lock can make all the difference.

    Continue to full article

  • 69th Mill Valley Fall Arts Festival

    69th Mill Valley Fall Arts Festival

    Two-day outdoor arts festival under the redwoods featuring 135 juried artists, interactive art, family activities, a Children's Grove, food, drinks, and community programming.

    Continue to full article

  • A Complete Checklist of Documents Needed for a Mortgage

    A Complete Checklist of Documents Needed for a Mortgage

    Navigating a mortgage application can feel overwhelming, especially with the amount of paperwork involved. As someone who’s guided clients through this process for over two decades—and as a full-service Mortgage Broker and direct lender—I want to simplify things for you. You’ll need to gather key documents: identification, pay stubs, tax returns, bank statements, and details on any debts or assets. If you’re self-employed or your financial situation is unique, expect to provide a few extra items. My approach is built on transparency and matching you with the best program, so having these materials ready helps us move efficiently toward your goals. With the right documents, we can focus on what matters: securing the optimal loan for you and your family.

    Continue to full article

  • Your Vested Pre-IPO Shares May Help You Qualify for a Mortgage

    Your Vested Pre-IPO Shares May Help You Qualify for a Mortgage

    Did you know that your vested pre-IPO shares could play a key role in qualifying for a mortgage—without needing to sell them? As someone who’s spent 23 years matching clients to tailored loan solutions, I look for every possible advantage to fit your unique financial picture. Lenders may assess vested pre-IPO shares using asset utilization, spreading their value over a qualifying term to calculate a monthly income figure. This approach can open new doors, especially for those with non-traditional income streams. My goal is always to provide transparent, creative options that put your interests first—so you can make fully informed decisions about your largest financial commitment.

    Continue to full article

  • Start With a Plan, Not a Listing

    Before you dive into home listings, let’s talk strategy. I always tell first-time buyers that a smart plan begins with understanding your complete financial picture—current income, debts, monthly expenses, and what you’d genuinely feel comfortable paying each month. The goal is for your mortgage to support your life, not overwhelm it.

    Check your credit early on. Even minor improvements—like fixing reporting errors or lowering balances—can lead to stronger loan offers and long-term savings. It’s a step I encourage with every client I work with, because it truly shapes your options.

    Don’t just save for the down payment. Set aside funds for closing costs, moving, and those inevitable first-month repairs. This extra preparation keeps you on track and helps you settle in smoothly, without surprises derailing your plans.

    And before you tour homes, get pre-approved. It sharpens your search, signals to sellers that you’re serious, and gives your offer more weight if there’s competition. As a broker who’s matched hundreds of families with the right loan program, I know how much this step matters.

    Finally, partner with a buyer’s agent who knows the local market and can spot issues early. Trust your plan, inspect the essentials, and keep a level head through closing. With the right preparation and guidance, you’ll find a home—and a mortgage—that truly fits.